
Insurance claim support, handled by the book.
A roof claim is a paperwork job. We document the damage, meet your adjuster on the roof, supplement missing line items in writing and chase the depreciation at closeout. Under Colorado Senate Bill 12-038 you get a written contract, a deductible statement, and 72 hours to cancel if your claim is denied.
Alta manages storm claims end to end for homeowners in Colorado Springs and Pueblo. We document the loss, meet your adjuster on the roof, supplement the scope in writing where line items are missing, and recover the withheld depreciation once the work is complete. We operate fully within Colorado Senate Bill 12-038, which means a written contract, a deductible statement in that contract, and your right to rescind within 72 hours if your claim is denied. We will never pay, waive or rebate your deductible, because in Colorado that is illegal.
What the law actually requires here.
Colorado Senate Bill 12-038 exists because storm seasons attract operators who do not stay. It requires a written contract on residential roofing work over $1,000, it requires that contract to state in writing that the contractor cannot pay, waive or rebate any part of your insurance deductible, and it gives you the right to rescind the contract within 72 hours of receiving written notice that your claim has been denied in whole or in part.
If a roofer offers to eat your deductible, cover it with a rebate, or bury it in a discount, they are asking you to participate in something the state legislature specifically prohibited, and they are putting your claim and your coverage at risk to win a signature. We will not do it, and we will tell you plainly when somebody else has offered.
Going deeper: the step by step roof insurance claim guide.
What do you actually get when we do this work?
We meet your adjuster on the roof
Not in the driveway. Standing on the roof with the adjuster, with our test squares still chalked, is where scope disagreements get resolved rather than appealed.
Supplements, in writing
First scopes routinely miss things: drip edge, ice-and-water where code now requires it, ventilation, starter course, steep or multi-storey access, or a second layer nobody knew was there. We submit supplements with the documentation attached.
Code upgrade coverage
Ordinance or Law coverage pays for bringing the roof up to current code even where the original roof did not have it. A lot of homeowners have this coverage and never use it. We identify the code-driven items and put them in the claim.
ACV first, then depreciation recovered
Your first check is normally actual cash value, the replacement cost minus the depreciation and your deductible. The withheld depreciation is released once the work is finished and the final invoice goes in. We chase that release, because that is the money most often left behind.
Your deductible, untouched
It is yours to pay, and it is the one number we cannot and will not move. Anyone who offers to is telling you how they treat rules generally.
Everything documented
Written contract, written scope, written supplements, photographs at every stage. If your claim ends up in a disagreement, documentation is the only thing that helps.
Honest about what is not covered
Wear and tear, deferred maintenance, old failed repairs and pre-existing leaks are not storm losses and carriers will treat them as such. We separate them out for you before you file.
Start to finish, no surprises.
- Step 01
Inspect first
We document before anything is reported, so you file with evidence rather than a hunch.
- Step 02
File correctly
Right date of loss, right cause, right elevations. Most problem claims were problems from the first phone call.
- Step 03
Adjuster meeting
We are on the roof with them and we walk the scope together.
- Step 04
Scope review
We read the carrier's estimate line by line and supplement what is missing, in writing.
- Step 05
Restore
Work proceeds against the approved scope, with change documentation if anything is discovered.
- Step 06
Recover & close
Final invoice submitted, depreciation released, warranty registered, claim closed out.
How the money actually moves
A hail claim on a replacement-cost policy usually arrives in two or three payments, not one. This is the sequence most Colorado homeowners see.
| Payment | What it is | When it lands |
|---|---|---|
| ACV check | Replacement cost less depreciation and your deductible | After the claim is approved |
| Your deductible | Paid by you, to the contractor. Never by the roofer | Due as the work proceeds |
| Supplement | Additional approved line items missed in the first scope | During the job |
| Recoverable depreciation | The withheld balance, released on proof of completion | After the final invoice |
| Upgrades you choose | Class 4, metal, colour or ventilation above the scope | Quoted separately, paid by you |
Swipe the table sideways to see every column.
Get it looked at before it gets worse.
Free, photo-documented and no obligation. We work Colorado Springs, Pueblo and the towns between them, and we run 24/7 emergency response including tarping if water is coming in right now.
Ask about insurance claim support
Tell us what you are dealing with and we will come and look at it.
Request received
Thanks. Someone from Alta Roofing will reach out shortly. Need us sooner? Call (719) 337-2126.
Insurance Claim Support questions.
We will not promise you it will not. Carriers set rates on regional loss history as well as your individual claims, and Colorado has been an expensive state for insurers for years. What we can do is make sure you only file when there is genuine, documented, claimable damage, because a denied claim can still appear on your loss history without paying you anything.
No. Colorado Senate Bill 12-038 prohibits a roofing contractor from paying, waiving or rebating any part of your deductible on a claim-funded job, and requires that statement in your contract. Any roofer offering otherwise is breaking state law and exposing your claim.
You have the right under Senate Bill 12-038 to rescind your contract with us within 72 hours of receiving written notice of the denial. Beyond that, a denial is not always final. We can request a reinspection with better documentation, and we will tell you honestly whether we think that is worth pursuing.
A request to the carrier to add line items the original scope missed, with documentation attached. Code-required ice-and-water, drip edge, ventilation, steep or high access, and a second layer discovered at tear-off are the usual ones. It is normal claim practice, not an argument.
It can. Some Colorado policies now carry a roof surfacing payment schedule or an actual-cash-value-only endorsement on older roofs, which means the carrier pays depreciated value and never releases recoverable depreciation. Check your declarations page, and we will read it with you.
On most replacement-cost policies, yes. The policy sets a window to complete the repairs and submit proof before the withheld depreciation is released, and the length varies by carrier. Find it on your policy before work starts. We schedule the job and send the final invoice so that window doesn't close on you.
No, and neither is any roofer. We are the contractor. We document the damage, we provide the estimate, we meet your adjuster and we supplement our scope. Negotiating your claim on your behalf is a licensed public adjuster's role, and we will say so rather than blur the line.
Other things we handle.
Roof Replacement
Complete tear-off and replacement in asphalt, metal, tile and TPO. Decking inspected and repaired, ice-and-water at the eaves and valleys, ventilation designed in, and a lifetime workmanship warranty on the install.
Read more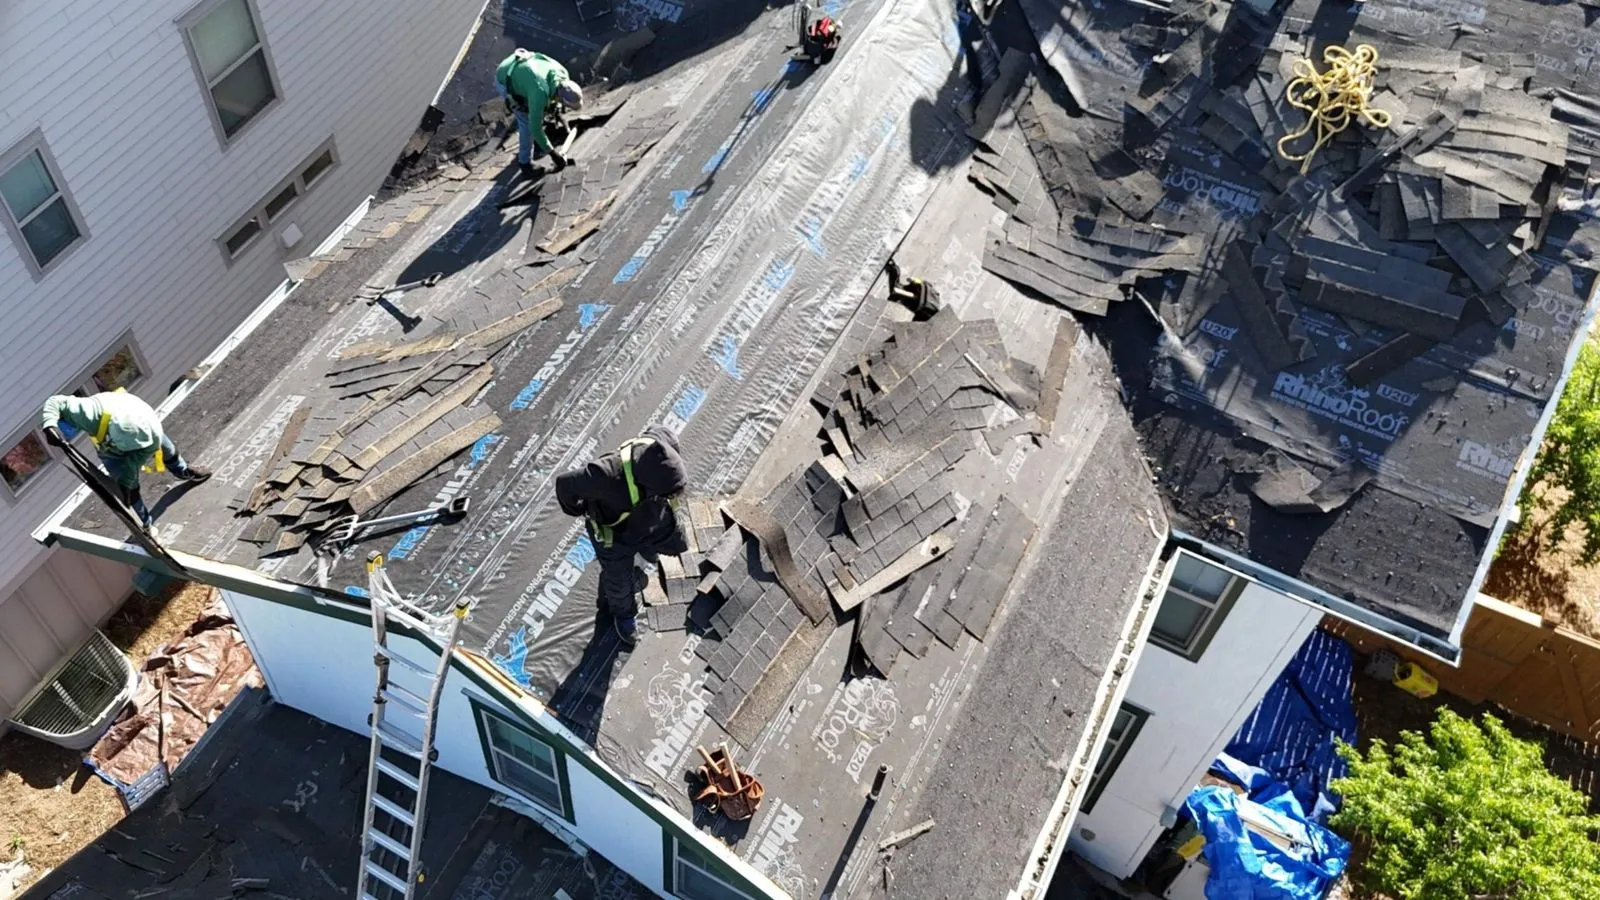
Roof Repair & Leak Detection
Honest, lasting fixes for leaks, missing shingles, failed flashing and storm punctures. We trace the source rather than patching the stain, and we run 24/7 emergency response including tarping.
Read more
Storm & Hail Restoration
Our specialty. We assess hail and wind damage with proper test squares, document every strike the way an adjuster scopes it, and restore the whole exterior back to pre-storm condition or better.
Read moreNeed insurance claim support? Start with the inspection.
Free, no obligation, no upsell. Twenty minutes with a local expert and you will know exactly where your roof stands.